Crisis - economic, financial and or environmental
15 articles
An economic or financial crisis is a period of strain, such as bank failures, widespread job losses or a sharp downturn, that squeezes household income and access to money. Start by confirming your deposits sit in an FDIC-insured bank, keeping some cash at home, and calling lenders early if a payment is at risk.
Severe crisis due to economic downturn, banking disruption, currency devaluation. Emphasis on resilience, bartering, and long-term self-sufficiency.
Updated
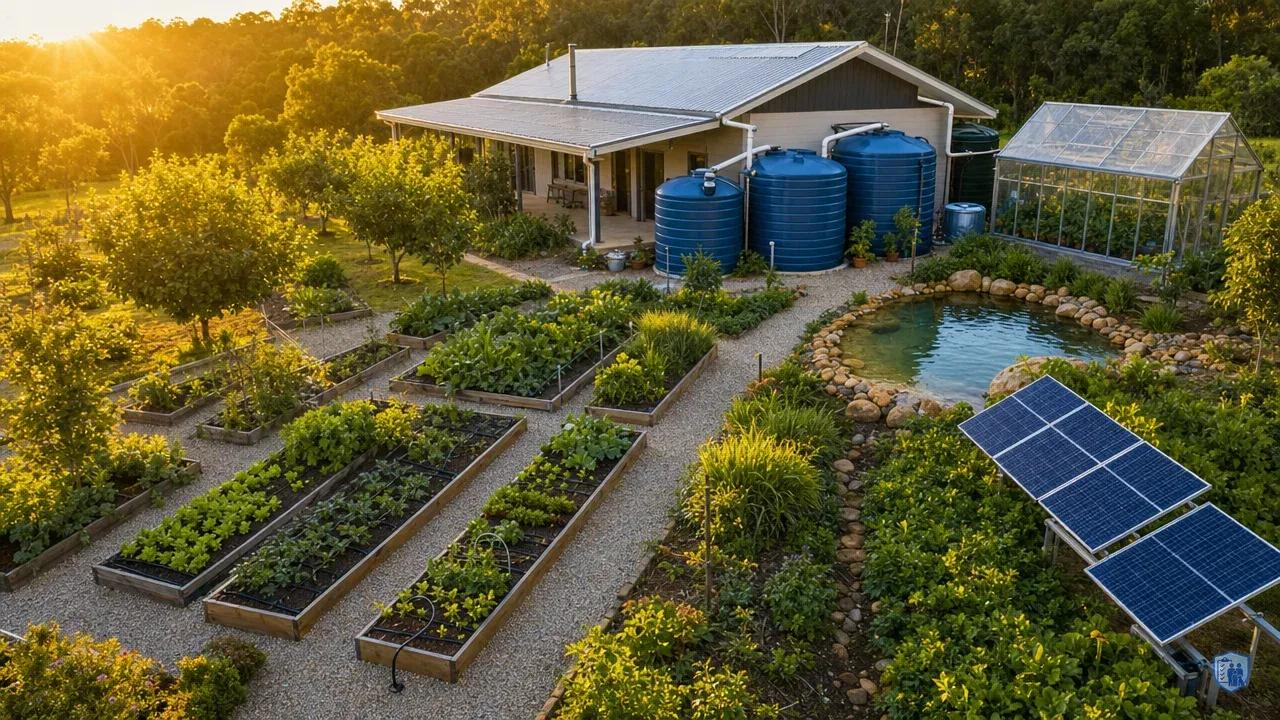
1-Acre Water Management: Irrigation and Rainwater Collection Systems
Municipal water systems collapse faster than food supply chains during economic crises. Engineer complete water independence for your one-acre property with professional-grade irrigation and harvesting systems.
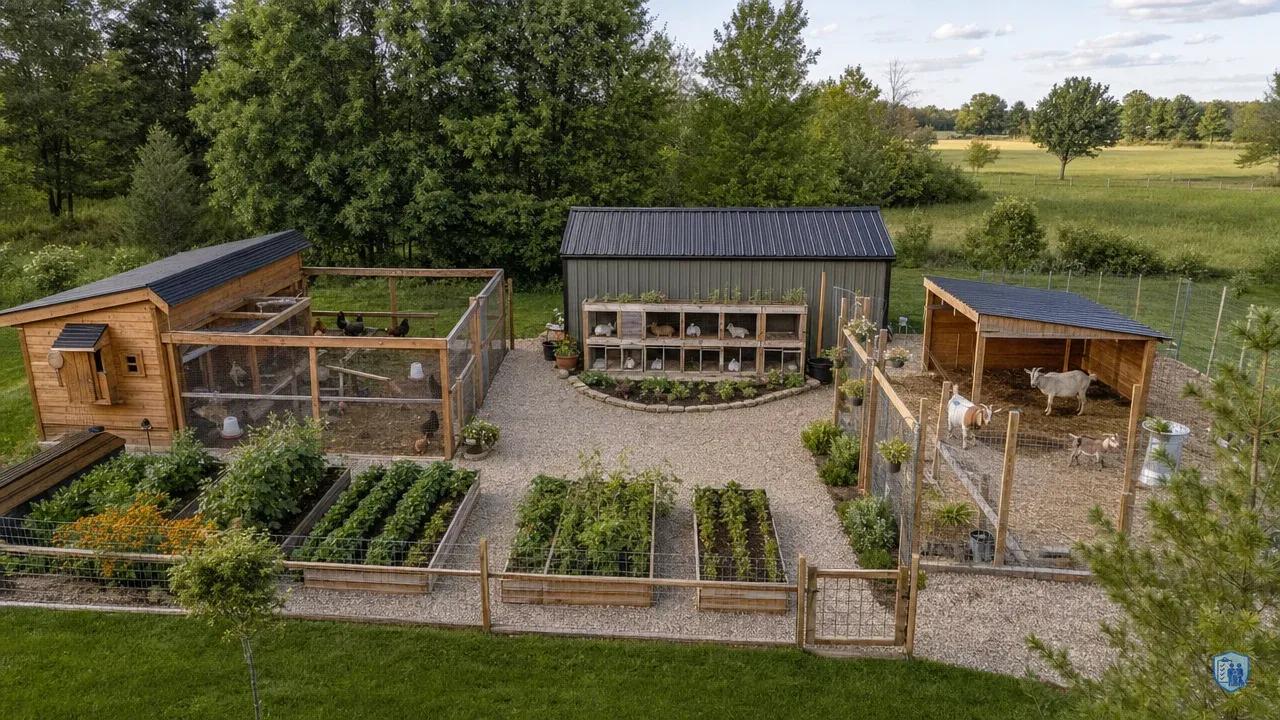
Small Livestock on 1 Acre: Chickens, Rabbits, and Goats for Protein
One acre can produce 60-80% of your family's annual protein needs. Compare chickens, rabbits, and goats for reliable food security beyond grocery stores.
Complete 1-Acre Self-Sufficiency Farming Guide: Feed Your Family Year-Round
One acre produces enough food for a family of four year-round—if you know which crops and systems actually work. Complete implementation blueprint inside.
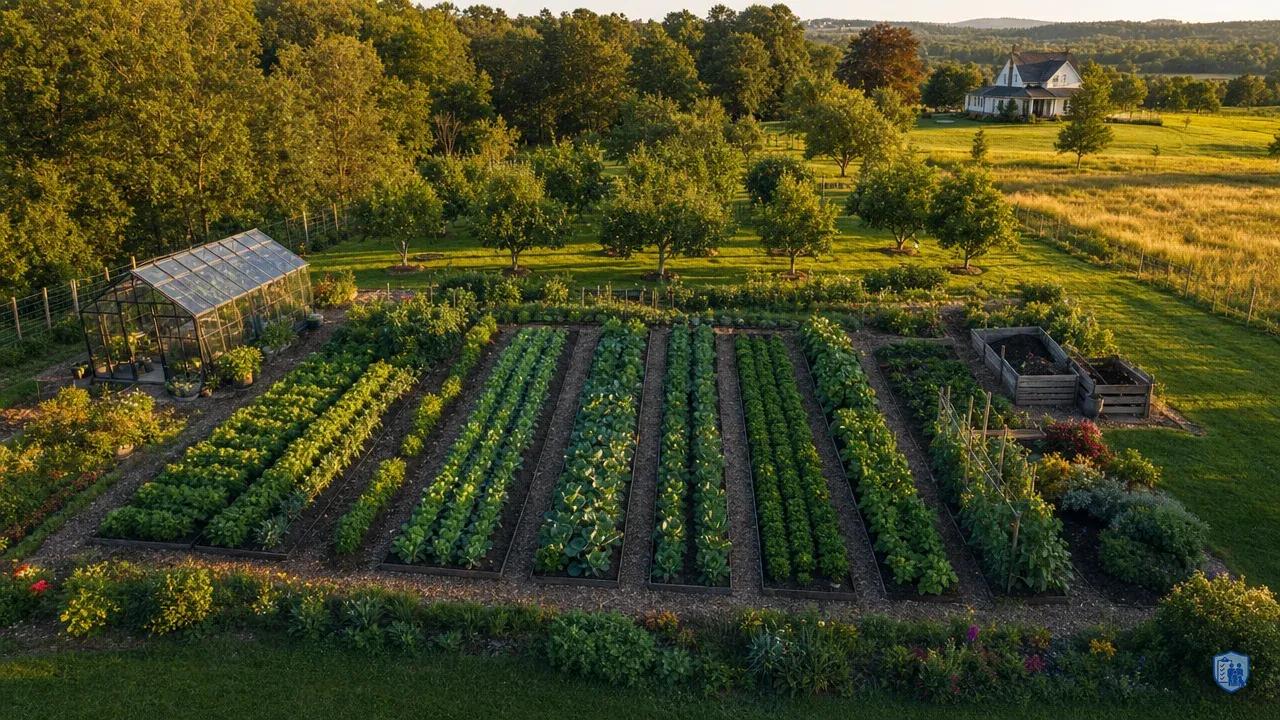
1-Acre Garden Layout: Zone Planning for Maximum Food Production
Random planting cuts your harvest in half. Zone-based planning produces 8,000-15,000 pounds annually on one acre—strategic layouts that turn land into crisis-proof food security.
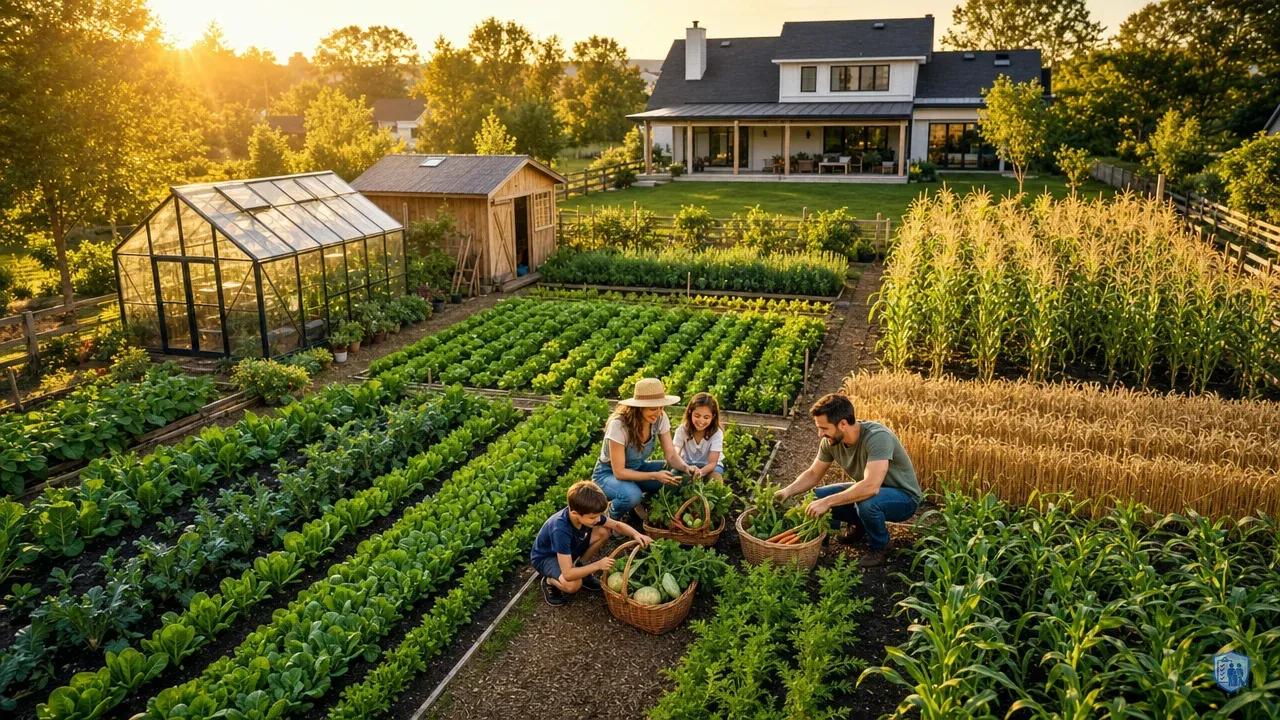
Best Crops for 1-Acre Food Security: High-Yield Vegetables and Grains
Most backyard gardens can't sustain a family through crisis. One acre with the right crops actually can—here's the practical blueprint.
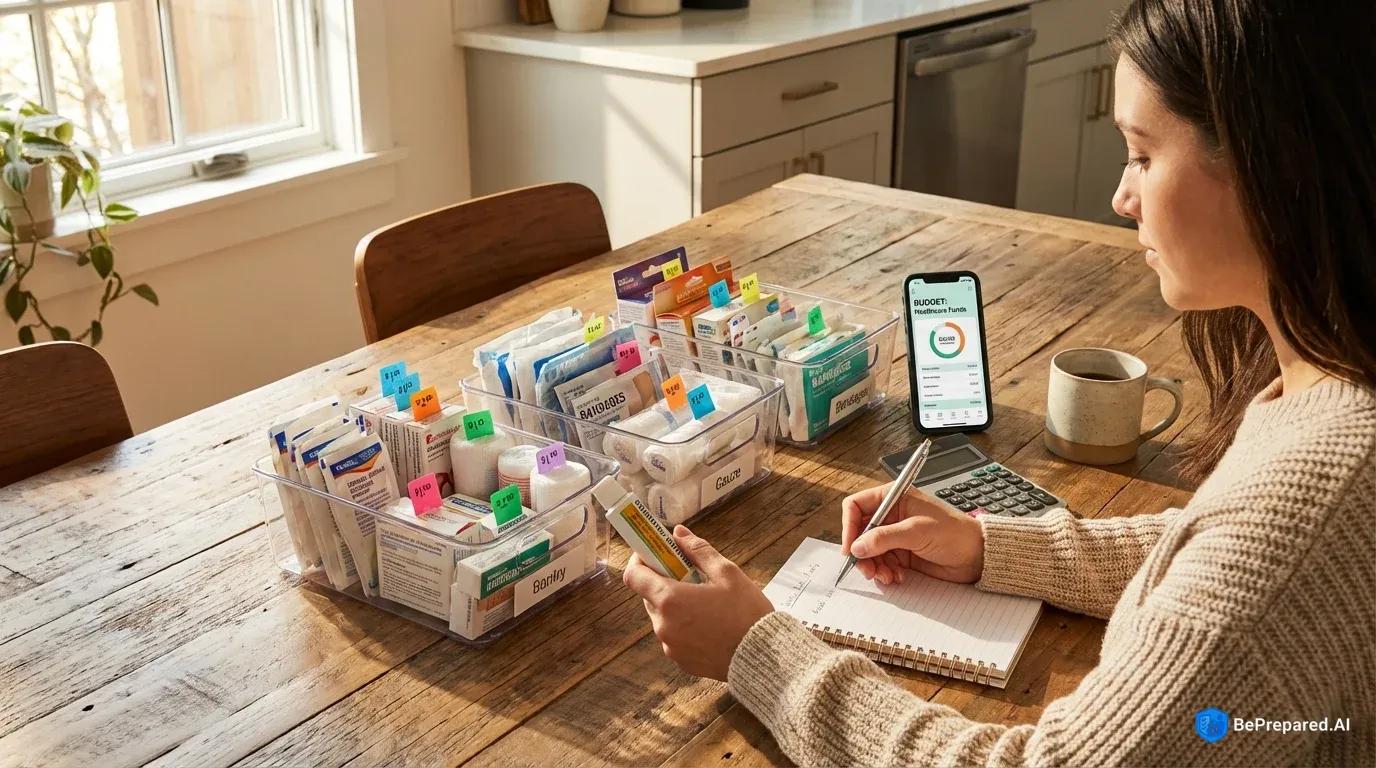
Building a Crisis Medical Kit on a Budget
Most emergency medical kits waste money on unlikely scenarios. Build a practical crisis kit for under $30 that handles 90% of real emergencies.
Top 10 Most Valuable Barter Items for Economic Crisis
Designer handbags lose value while aspirin becomes gold during economic collapse. Discover which everyday items transform into tradeable currency when money fails.
Neighborhood Security Planning for Economic Crisis
Property crime surges 7-12% during economic downturns, but most neighborhoods ignore predictable warning signs. Build coordinated security before crisis hits.
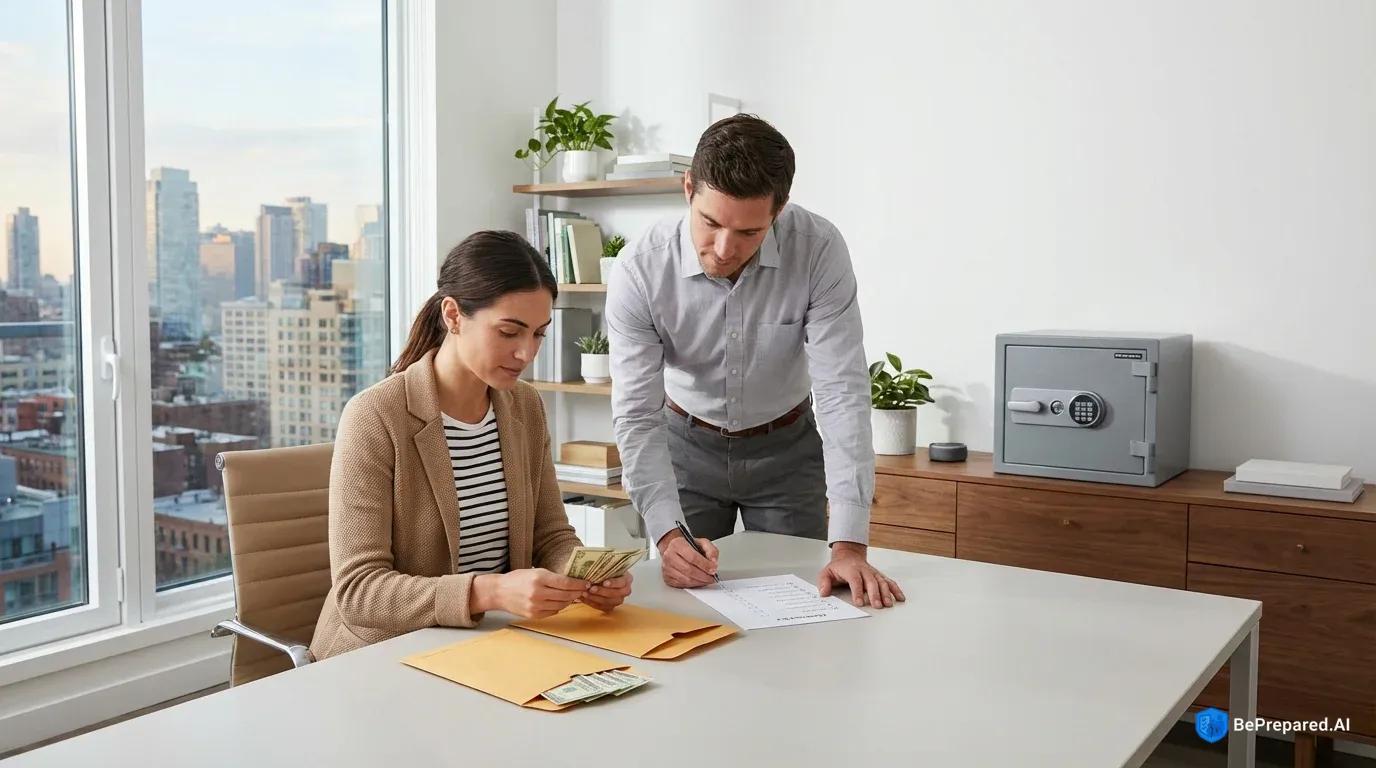
Home Cash Storage: How Much Money to Keep During a Banking Crisis
FDIC insurance doesn't mean instant access to your money. Calculate exactly how much cash to store at home when banking systems fail.
Complete Financial Crisis Survival Guide: Protecting Your Family During Economic Collapse
ATM failures and payment system crashes hit ordinary families first during economic disruptions. Build your financial safety net before the next crisis.
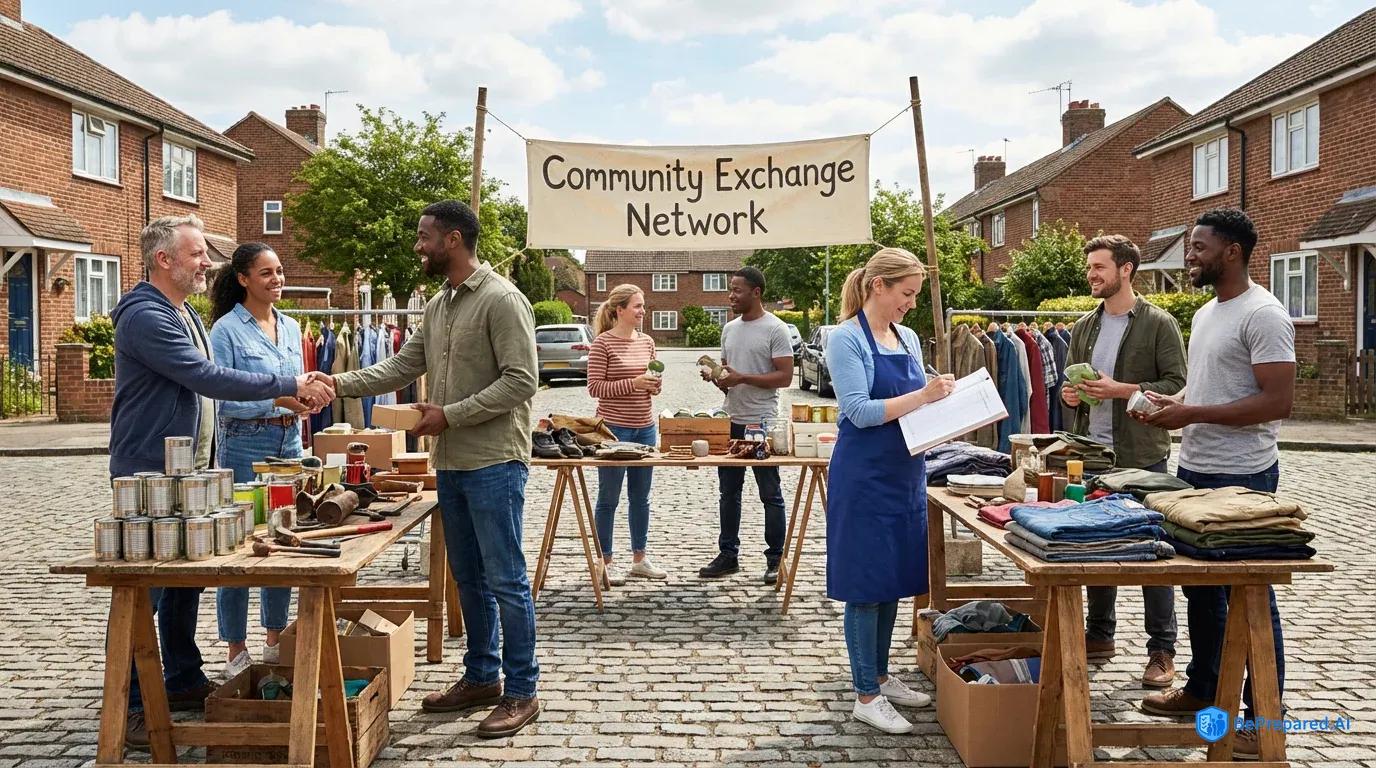
Alternative Currency Guide: Understanding Barter and Trade During Crisis
Barter networks expand 3-4x during monetary crises, yet most people wait until collapse. Build functional alternative currency systems before you need them.
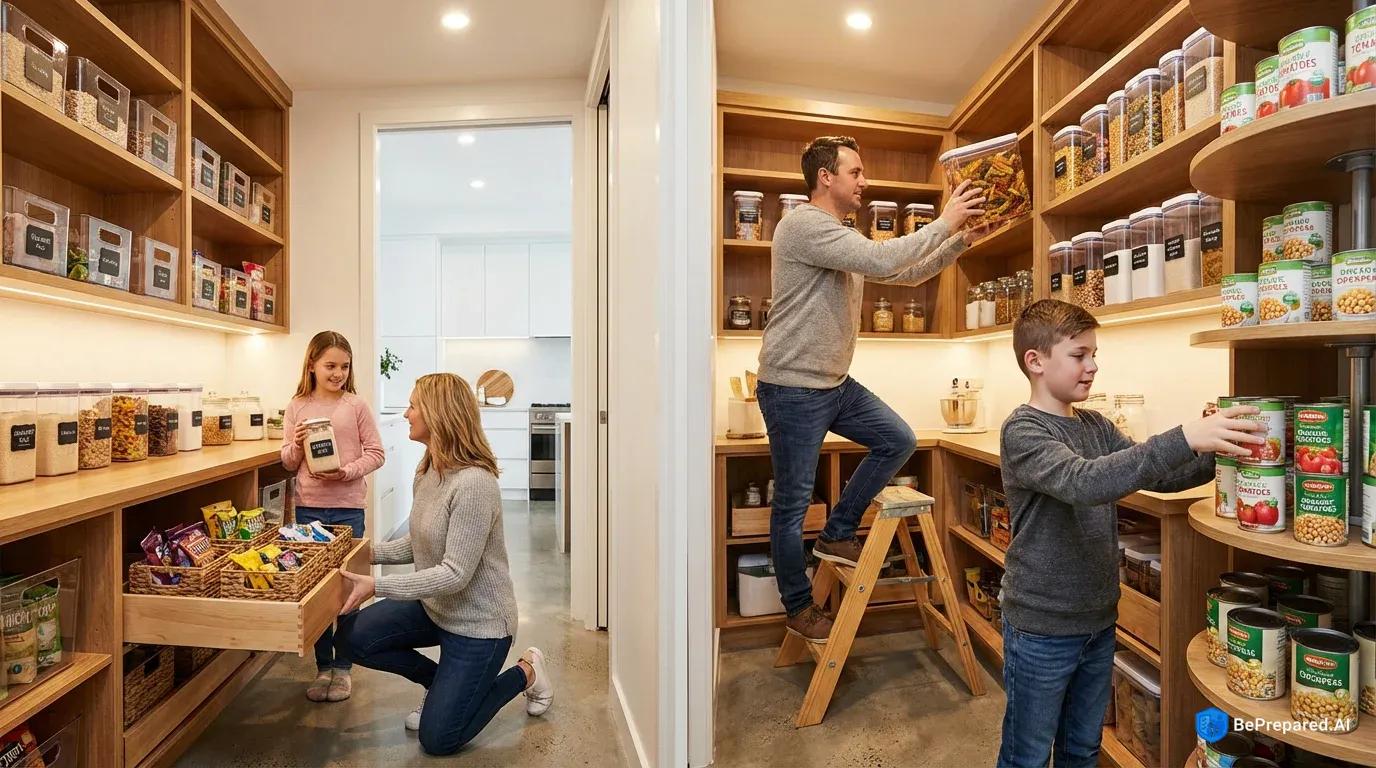
Financial Crisis Food Storage: Complete Pantry Planning Guide
Most families have just 3 days of food at home. This friendly guide shows how to build months of pantry security without bunkers or freeze-dried meals.
5 Common Mistakes in Financial Crisis Preparation
57% of Americans can't cover a $1,000 emergency. These five avoidable mistakes explain why—and how to fix them before crisis strikes.
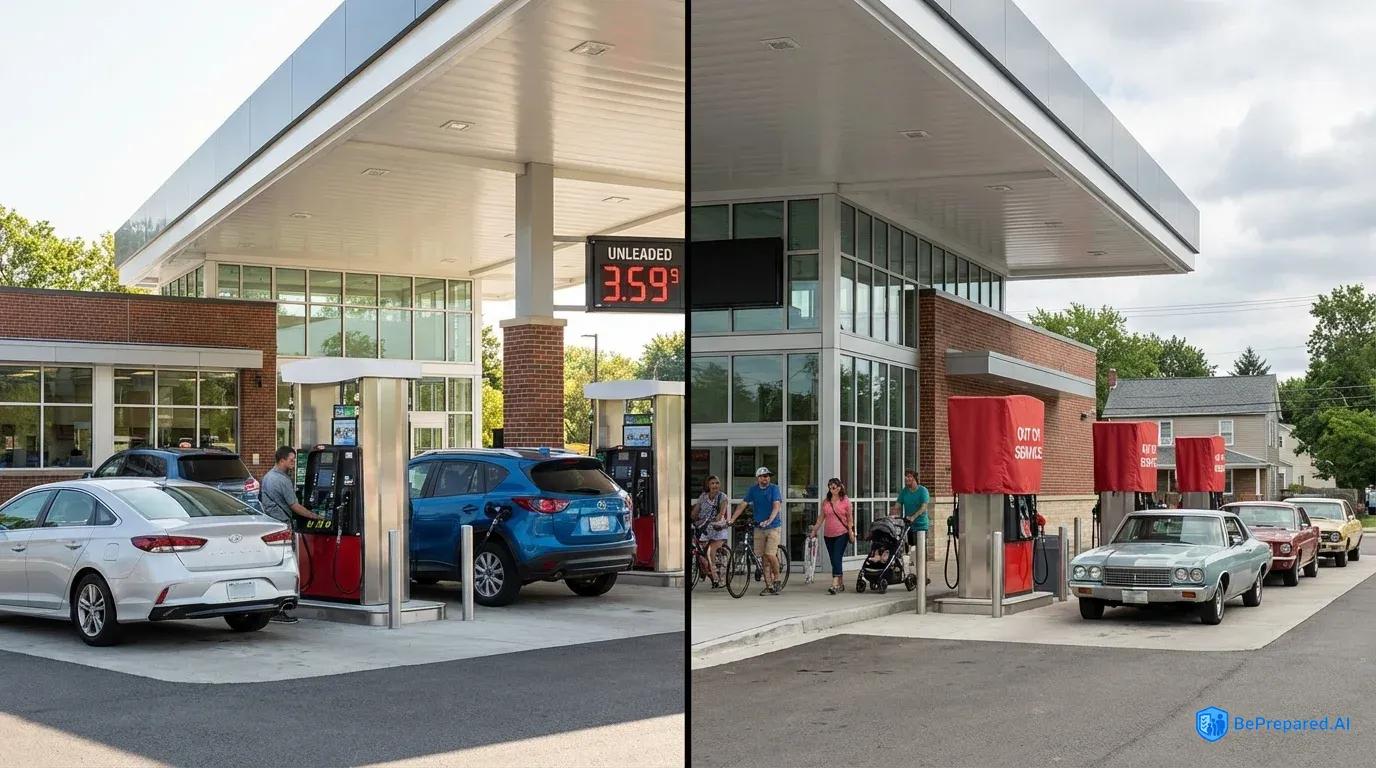
Crisis Transportation Plan: When Fuel Becomes Scarce
Communities with backup transportation plans survive fuel shortages 60% better than car-dependent ones. Build your multi-layered mobility strategy before pumps run dry.
10 Essential Items to Buy Before a Financial Crisis
What to buy before money gets tight: food and water staples, first aid supplies, and the documents and cash reserve to have ready in advance.
Ready to stock up? See our Crisis - economic, financial and or environmental kits.
Is the money in our bank account safe if a bank fails?
If your bank is FDIC-insured, your deposits are protected up to $250,000 per depositor, per bank, for each account ownership category. The FDIC says that since it was founded in 1933, no depositor has lost a penny of insured funds. Checking, savings, money market deposit accounts and certificates of deposit are covered. Stocks, bonds, mutual funds, annuities, crypto assets and safe deposit box contents are not, even when offered by an insured bank. Joint accounts and certain retirement accounts such as IRAs are separate ownership categories with their own coverage. Confirm your bank is insured with the FDIC's BankFind tool, and use its EDIE estimator if your balances are near the limit.
How much cash should we keep at home for an emergency?
Keep a small amount of cash at home in a safe place, with small bills on hand. Ready.gov's reasoning is practical: ATMs and credit cards may not work during a disaster, just when you need fuel, food or supplies. The Consumer Financial Protection Bureau notes the tradeoff, since cash at home can be stolen, lost or destroyed. A bank or credit union account is generally considered one of the safest places for savings. A reasonable balance is a modest cash reserve at home, with the rest of your emergency savings in an insured account. Store your account numbers and your bank's contact details with your other important papers.
Who should we call if we cannot make a loan or bill payment?
Call your lender before you miss the payment and ask what options it offers. Ready.gov advises contacting your bank right away to discuss options, rather than skipping payments or acting against your loan terms. The CFPB suggests asking creditors such as your landlord, utility companies and card issuers whether due dates can be moved to line up with when your income arrives. Be wary of unsolicited help. Scammers target money worries with debt consolidation offers, work-from-home schemes and student loan repayment plans, and the government will not call or text you about owing money. If someone claiming to be a government agent contacts you, report it at ftc.gov/complaint.
Sources
- Understanding Deposit Insurance, Federal Deposit Insurance Corporation. $250,000 per depositor, per FDIC-insured bank, per ownership category; no depositor has lost a penny of insured funds since 1933; covered and non-covered products; joint and IRA accounts are separate categories; BankFind and EDIE tools.
- Financial Preparedness, Ready.gov (FEMA). Keep a small amount of cash at home in a safe place, with small bills, because ATMs and credit cards may not work in a disaster; contact your bank before skipping loan payments; scam warnings about debt consolidation, work-from-home and student loan offers; government will not call or text about owing money; report at ftc.gov/complaint; keep banking contacts with your records.
- An essential guide to building an emergency fund, Consumer Financial Protection Bureau. Cash at home can be stolen, lost or destroyed; a bank or credit union account is generally considered one of the safest places to keep savings; work with landlords, utilities and card companies to adjust bill due dates.